The number is only the beginning.
Why a useful earnings bridge starts a conversation rather than ends one.
A bridge is a set of judgments.
Reported EBITDA is a starting point. The value of a quality of earnings exercise lies in understanding which parts of that result reflect the business a buyer will actually own. A proposed adjustment is a claim about that future business, and the claim deserves evidence.
Take owner compensation. An add-back is incomplete without a view on the cost of replacing the owner's role. Removing every euro of compensation may produce a neat spreadsheet, but it does not describe the operating model after the transaction.
Keep the source beside the conclusion.
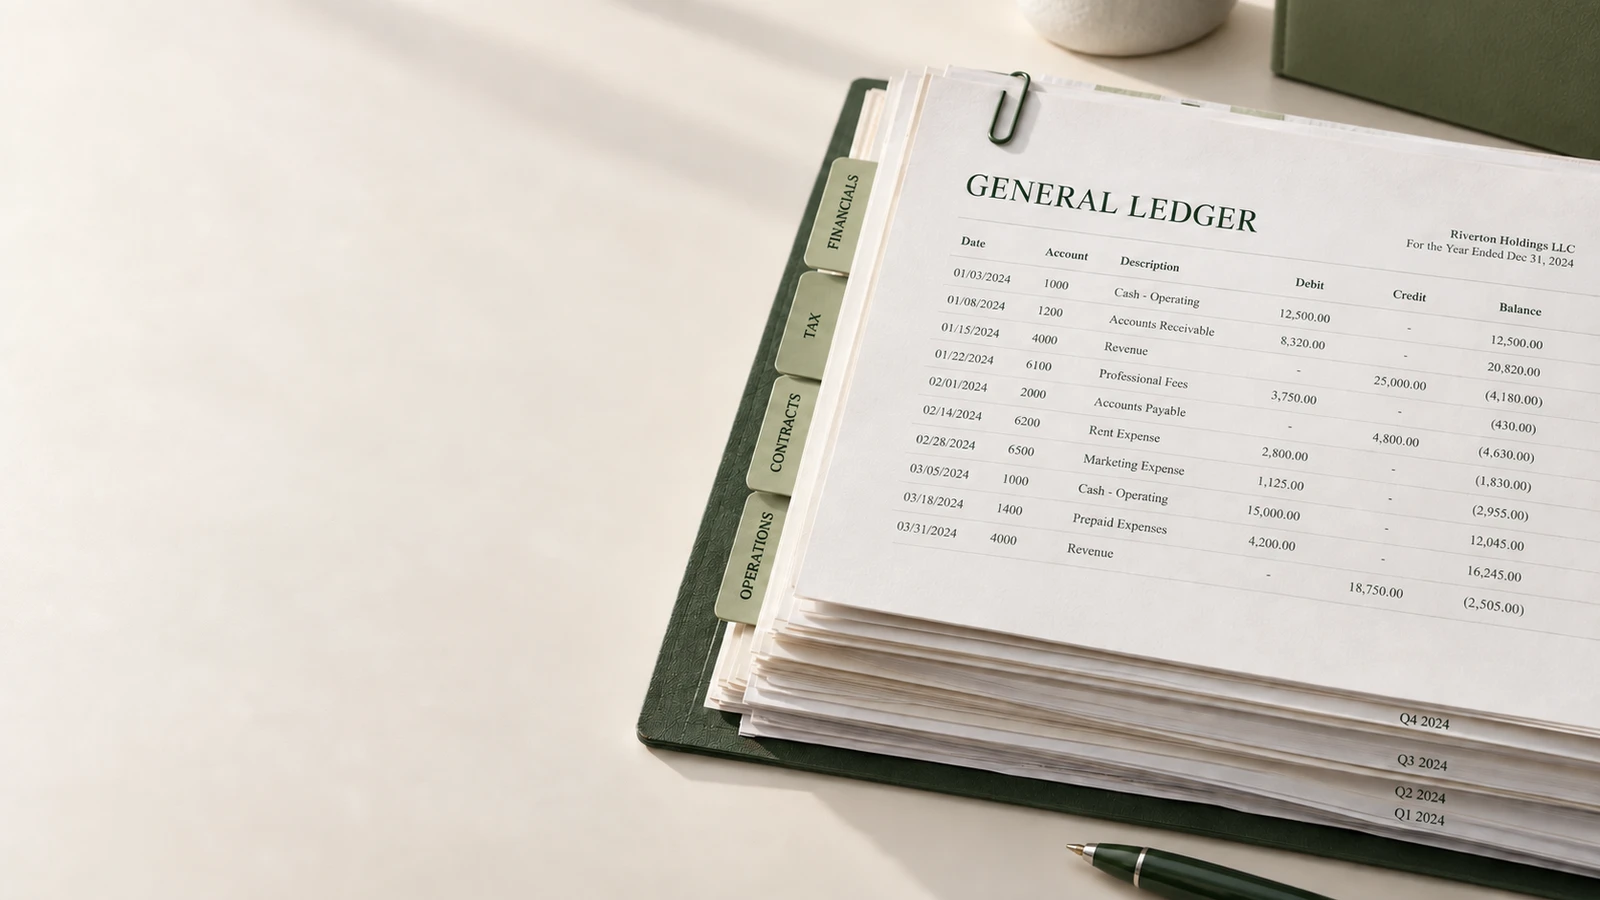
Each proposed adjustment should lead back to the selected ledger entries, a supporting document, and an explanation a reviewer can follow. If that path is difficult to reconstruct, the adjustment is difficult to challenge and difficult to defend.
This is why the findings register sits at the center of the AI Assure concept. The chart, the source, the management question, and the review status are different views of the same issue. They should remain connected as the engagement progresses.
An unresolved question is useful information.
A good diligence process makes uncertainty visible. If a legal cost is labeled non-recurring, the team still needs to confirm what the expense relates to, whether a similar expense is likely to recur, and which evidence supports the conclusion.
The resulting number can be calculated precisely while the proposed treatment remains open. Keeping those two facts separate gives a reviewer a clearer basis for deciding what belongs in the final bridge.
Examples describe a fictional engagement and are intended to illustrate the product workflow.
Explore the sample engagement